


giuseppehardma
About giuseppehardma
The Angelina Jolie Guide To Housing
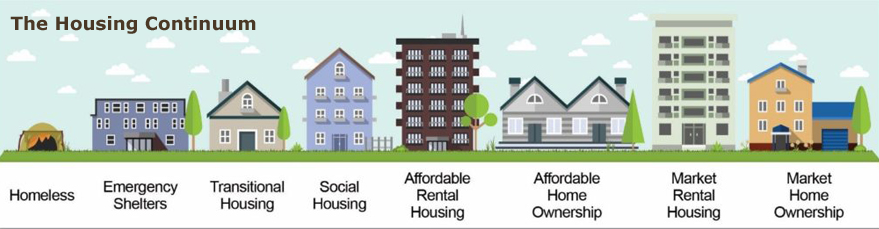 There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
The arithmetic here is brutal and worth understanding clearly. A buyer who financed a $400,000 home at three percent in 2021 pays roughly $1,686 per month on principal and interest. That same loan at a seven percent rate costs $2,661. Those numbers explain why the market froze rather than crashed when rates moved higher. Volume collapsed. Prices mostly did not.
Here is what that creates for someone who is financially prepared and ready to move: more room to negotiate than the market’s reputation suggests. The panic buyers are gone. The buyers who showed up with emotion instead of analysis have mostly sat back down. What remains is a more functional market, even if it is not a cheap one.
 Before you look at a single listing, get your mortgage pre-approval completed and in hand. Not a rough estimate. Not a verbal confirmation from a loan officer you met once. A full pre-approval based on verified income, tax returns, bank statements, and a hard credit pull. Without that letter, you are not a buyer, you are a browser.
If the report surfaces problems that go well beyond normal wear and tear, you have real choices, and walking away is a legitimate one of them. You can walk away if the scope of the problems makes the agreed price no longer reasonable. Signing off on a failing roof or a bad HVAC system is not the same house you made an offer on.
Negotiation works best when it is quiet and well-prepared. Before you make an offer, find out how long the listing has been active. A listing that has been relisted after a cancellation is a fundamentally different negotiation than a fresh listing in a neighborhood where homes sell in under a week.
 The timing question, whether to buy now or wait for rates to come down, is the one that trips up more buyers than any other single factor. The record on market timing for owner-occupied housing is not encouraging. The more useful question is not whether now is the right time in the abstract; it is whether you are buying because the numbers make sense for you, not because you feel social pressure to own.
 Real estate rewards preparation more than it rewards timing. Waiting for a better market is a reasonable position only if your personal situation supports it, otherwise you are just paying rent while prices hold. A look at real estate listings and pricing data in your target area costs nothing and tells you a great deal.
No listing found.